Private lenders rarely manage one file at a time. A team may have dozens or hundreds of loans moving through intake, document collection, underwriting, conditions, approval, funding, and servicing handoff at once. Loan pipeline management gives lenders a way to see where every deal stands, what needs attention, and which files are likely to fund.
When that visibility depends on spreadsheets or manual updates, the pipeline becomes harder to trust. A file can look active when it is stalled. A manager may miss an aging condition. A borrower may wait while the team figures out who owns the next task.
A stronger pipeline process helps lenders prioritize work, reduce bottlenecks, forecast funding volume, and move qualified loans from application to funding with more control.
What Is Loan Pipeline Management?
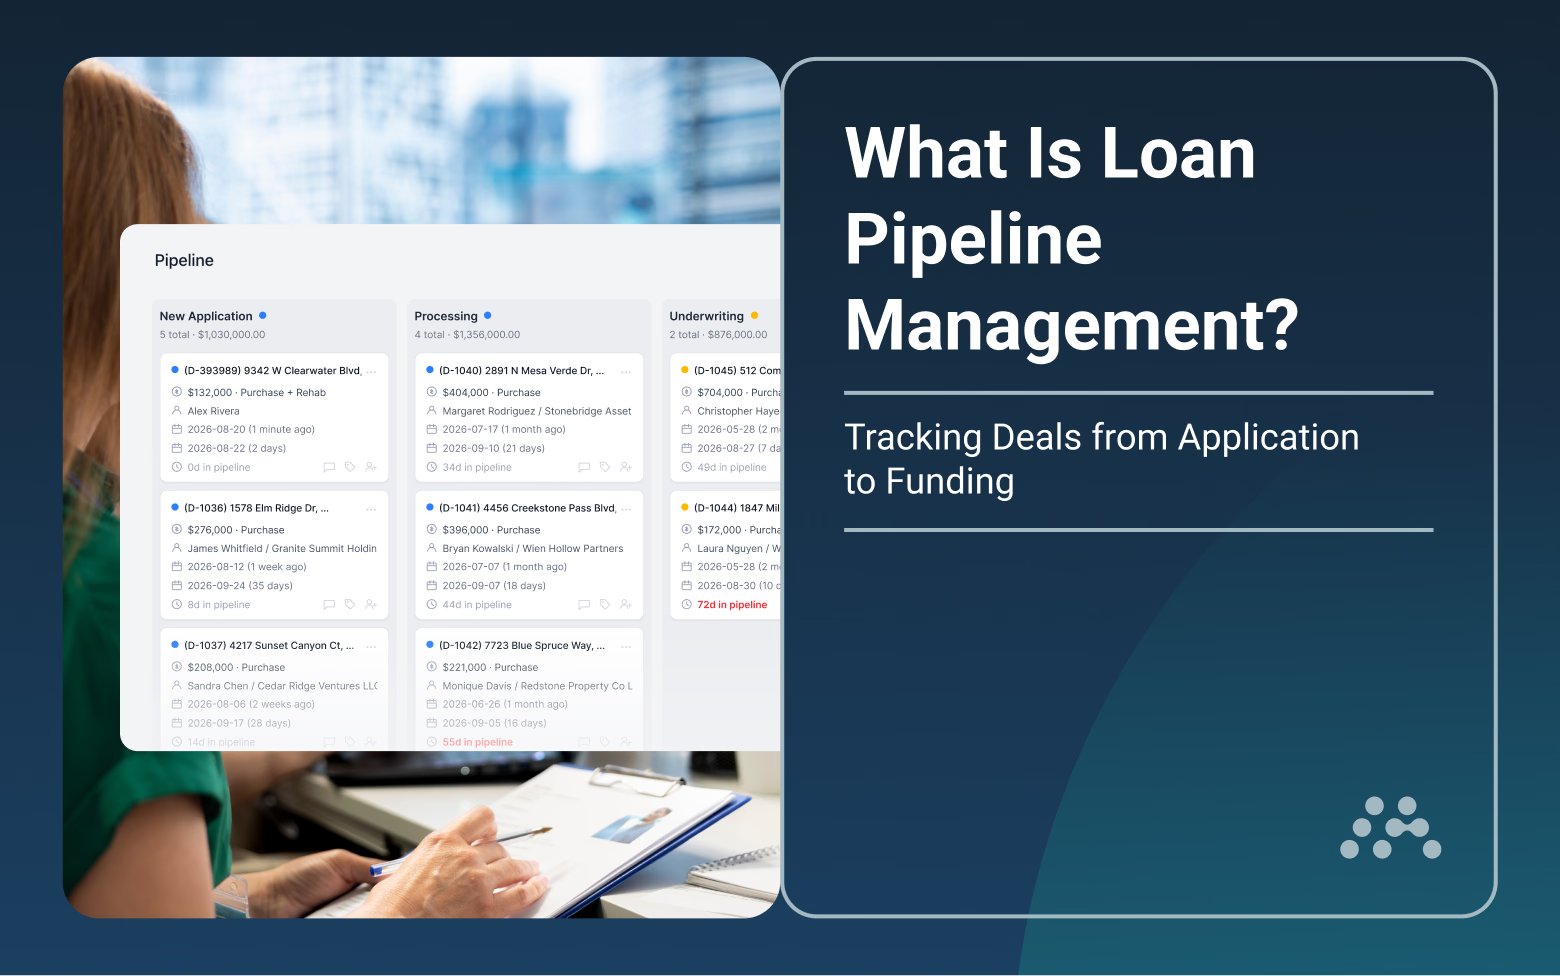
Loan pipeline management is the process of tracking and managing loans as they move from application through funding. It gives lending teams a structured view of every file in progress, including its stage, owner, missing items, next action, expected timeline, and funding status.
A loan pipeline usually includes:
- new leads or applications
- pre-qualified files
- documents requested or received
- files in underwriting
- open conditions
- approved loans
- loans ready for closing
- funded loans
- files transferring to servicing
The pipeline is different from a single loan file. A loan file shows what is happening with one deal. Pipeline management shows how the full book of in-progress work is moving.
That distinction matters for private lenders. A single file may be moving smoothly, while the overall pipeline is building risk. Too many files may be waiting on documents. Underwriting may be overloaded. Approved loans may be sitting before funding. Borrower follow-up may be slowing down the whole process.
Strong pipeline visibility helps managers see those patterns before they affect closing timelines. It also helps teams decide which files need attention first, where workload is building, and how much funding volume is likely to close in the coming weeks.
Mortgage Automator’s loan origination tools help lenders manage the work between application and funding with connected workflows, task tracking, documents, and pipeline visibility.
Understanding the Mortgage Loan Origination Pipeline
A mortgage loan origination pipeline follows the file from first contact to funding. Each stage has a different purpose, and delays in one stage can create pressure later.
Lead or Application Received
This is where the deal enters the system. The lender may receive an application through a form, broker submission, referral, or internal intake process. The goal is to capture enough information to decide whether the file is worth moving forward.
Pre-Qualification
Some lenders use pre-qualification to decide whether the borrower, collateral, loan amount, and requested terms fit their criteria. A weak pre-qualification process can fill the pipeline with files that are unlikely to close.
Document Collection
Borrowers, brokers, guarantors, or referral partners submit the information needed for review. Missing documents are one of the most common reasons files stall. A strong process tracks what has been requested, what has been received, and what still needs review.
Underwriting
Underwriting tests the deal. The team reviews borrower details, collateral, loan purpose, repayment strategy, risk, conditions, and supporting documents. Files can slow down here when reviewers lack complete information or when ownership is unclear.
Conditions Management
Conditions are the items that must be resolved before approval, closing, or funding. This stage needs tight tracking because one unresolved condition can hold the loan even when most of the file is complete.
Approval
Approval confirms the lender is prepared to proceed, often subject to final terms, documents, or closing requirements. The approval stage should create a clear path to closing rather than another round of manual coordination.
Funding
Funding depends on final documents, accurate loan terms, signed agreements, payment setup, and internal authorization. Delays at this stage can affect borrowers, brokers, investors, and internal forecasts.
Transfer to Servicing
Once the loan funds, the file needs to move into servicing with accurate terms, payment details, borrower records, documents, and notes. A weak handoff can create problems after the loan is already active.
Why Mortgage Loan Pipeline Management Matters
Mortgage loan pipeline management gives lenders more than a list of active files. It gives the team a live view of operational pressure.
The benefits usually show up in a few areas:
- Increased visibility: Managers can see where each loan sits, who owns it, and what needs to happen next.
- Better forecasting: Funding forecasts become more reliable when the team can see expected closing dates, stage movement, and aging files.
- Faster loan processing: Files move faster when missing items, stalled tasks, and review bottlenecks are visible earlier.
- Improved borrower experience: Borrowers get faster updates when staff can see file status without chasing emails or spreadsheets.
- Better resource allocation: Managers can see whether underwriting, processing, closing, or document collection is becoming overloaded.
- Reduced operational risk: Pipeline visibility helps catch missing conditions, compliance gaps, and delayed approvals before they affect funding.
- Improved team accountability: Clear ownership makes it harder for files to sit between departments.
- Stronger compliance: A structured pipeline helps preserve task history, review steps, documents, and approval activity.
A pipeline problem usually starts small. A borrower has not sent a document. A reviewer has not picked up the file. A condition was cleared, but the status was never updated. A closing date has moved, but the funding forecast still shows the old timeline.
When teams rely on manual updates, those small gaps become difficult to spot. A dashboard or workflow system helps managers see the pipeline as it is, rather than as it was during the last manual update.
How to Build a Loan Pipeline
Learning how to build a loan pipeline starts with the operational process, not the report. A useful pipeline should show how work actually moves from application to funding.
Define Standard Pipeline Stages
Start by naming the stages every file moves through. These may include application received, pre-qualification, document collection, underwriting, conditions, approval, closing, funding, and servicing handoff.
The stages should be specific enough to show where the loan is stuck. A pipeline with only “open,” “approved,” and “funded” gives managers very little operational insight.
Create Consistent Workflows
Each stage should have clear requirements. Staff should know what must happen before a file moves forward, what documents are required, and which tasks should be completed.
Consistent workflows reduce the need for side conversations. They also make it easier to onboard new team members because the process is visible inside the system.
Assign Ownership at Every Stage
A pipeline breaks down when no one knows who owns the next step. Every file should have a current owner, whether that is a processor, underwriter, loan officer, closer, or manager.
Ownership should also change when the file moves. A loan in underwriting needs different attention than a loan waiting on final signatures.
Automate Task Management
Workflow automation helps reduce the number of manual reminders needed to move files forward. Tasks can be triggered when a loan enters a stage, when a document is missing, when a condition is cleared, or when a deadline is approaching.
Automation is most useful when it supports the team’s actual process. It should help staff act sooner, not create alerts that everyone learns to ignore.
Centralize Documents and Communications
The pipeline is only reliable if the underlying file is reliable. Documents, borrower messages, broker updates, internal notes, approvals, and conditions should stay tied to the loan record.
This prevents staff from searching through inboxes or shared folders just to understand the latest status.
Monitor Pipeline Health with Dashboards
A dashboard should show both volume and movement. Useful views include active loans by stage, aging files, upcoming funding, stalled tasks, missing documents, and team workload.
This helps managers focus attention where it matters instead of asking each team member for a status update.
Review Pipeline Performance Regularly
A pipeline should improve over time. Regular reviews can show whether files are spending too long in one stage, whether fallout is increasing, or whether certain loan types need a different workflow.
Building a loan pipeline is an ongoing operating discipline. The goal is to create a process that helps qualified loans move forward without hiding bottlenecks until the closing date is at risk.
Common Pipeline Bottlenecks That Delay Funding
Most funding delays come from ordinary workflow issues that repeat across the pipeline. The most common bottlenecks include:
- Missing documentation: Underwriters cannot complete reviews when the required borrower, entity, collateral, or income documents are incomplete.
- Manual approvals: Files slow down when approvals depend on email follow-up or someone remembering to check the next step.
- Slow borrower responses: Borrowers may not know what is missing or what needs urgent attention.
- Underwriting delays: Review teams can become overloaded when files arrive incomplete or poorly prioritized.
- Compliance reviews: Required steps may sit too late in the process if they are not built into the workflow.
- Communication gaps: Borrowers, brokers, processors, and underwriters may all be working from different information.
- Task ownership confusion: Files stall when no one is clearly responsible for the next action.
- Duplicate data entry: Copying details across systems increases errors and slows review.
- Limited visibility: Managers cannot fix a bottleneck they cannot see.
Identifying bottlenecks gives lenders a more practical way to improve loan processing. Instead of pushing the whole team to “move faster,” managers can see exactly where files are losing time.
A loan pipeline health dashboard can help visualize active loans, stage distribution, aging files, approval rates, pull-through rates, and projected funding volume.
Key Metrics to Track in Loan Pipeline Management
Good pipeline management depends on useful metrics. Lenders should track more than total applications or total funded loans.
Important KPIs include:
- Number of active loans: Shows current workload across the team.
- Stage conversion rates: Shows how many files move from one stage to the next.
- Pipeline aging: Identifies files that have been sitting too long.
- Time in each stage: Helps locate delays in intake, documents, underwriting, approval, or funding.
- Approval rate: Shows how many reviewed files become approved loans.
- Pull-through rate: Measures how many applications or approvals eventually fund.
- Funding volume: Helps forecast revenue, capital needs, and operational workload.
- Fallout rate: Shows how many files drop out and where that happens.
- Average time to close: Measures the overall speed of the origination process.
These metrics support better decisions. If document collection is taking too long, the team may need clearer borrower requests or portal-based uploads. If underwriting time is increasing, managers may need to review file quality before submission. If pull-through is falling, the lender may need to look at lead quality, pricing, borrower fit, or approval conditions.
The value of pipeline metrics comes from regular review. A dashboard that no one checks will not improve performance. Teams should use these numbers to adjust workflows, rebalance workload, and prioritize aging files before they create closing pressure.
How Mortgage Automator Simplifies Loan Pipeline Management
Mortgage Automator helps private lenders manage the mortgage loan pipeline from application through funding with connected workflows, automation, documents, reporting, and borrower records.
The platform supports:
- Workflow automation: Route files, tasks, approvals, reminders, and next steps through defined stages.
- Pipeline dashboards: Give managers visibility into active loans, stage movement, and files that need attention.
- Task management: Assign ownership across processors, underwriters, closers, administrators, and managers.
- Automated notifications: Trigger reminders for missing documents, borrower follow-up, internal tasks, and workflow deadlines.
- Document management: Keep borrower files, approvals, conditions, and supporting documents tied to the loan.
- Team collaboration: Help staff work from the same loan record instead of scattered updates.
- Reporting: Track pipeline performance, funding timelines, workload, and operational trends.
- Compliance tracking: Keep required steps, records, and review activity connected to the file.
- Centralized borrower records: Maintain borrower details, communication, documents, and loan history in one place.
Common Mistakes in Mortgage Loan Pipeline Management
A pipeline can look organized and still hide risk. Lenders should watch for these mistakes:
- Managing loans in spreadsheets: Spreadsheets can track status, but they rarely show task ownership, document history, communication, and workflow movement in one place.
- Using inconsistent pipeline stages: If teams define stages differently, reports become harder to trust.
- Skipping standardized workflows: Without clear requirements by stage, staff may move files forward before they are ready.
- Relying on manual reporting: Reports built by hand are often outdated by the time managers review them.
- Allowing poor communication: Borrowers and brokers need clear updates, and internal teams need the same view of file status.
- Ignoring pipeline analytics: Lenders miss patterns when they do not review aging, conversion, fallout, and time-in-stage data.
- Failing to prioritize aging loans: Older files need active review before they quietly clog the pipeline.
- Underusing automation: Manual reminders, follow-up, and status updates consume time that could be spent moving files forward.
These mistakes reduce efficiency and increase operational risk. More importantly, they make the pipeline harder to manage as volume grows.
Final Thoughts
A healthy loan pipeline gives lenders a clearer view of the work between application and funding. It shows which files are moving, which ones are stuck, who owns the next step, and how much volume is likely to close.
The strongest pipeline processes are built around consistent stages, clear ownership, centralized records, real-time dashboards, and workflow automation. That structure helps teams reduce bottlenecks, improve borrower communication, and make better funding forecasts.
For private lenders, pipeline management should be treated as an operating discipline, not a sales report. The right technology gives teams the visibility to manage every loan in progress with more confidence.
Frequently Asked Questions
What is loan pipeline management?
Loan pipeline management is the process of tracking loans from application through funding. It helps lenders see each file’s status, owner, missing items, next step, and expected funding timeline.
What are the stages of a mortgage loan pipeline?
Common stages include lead or application received, pre-qualification, document collection, underwriting, conditions management, approval, funding, and transfer to servicing. Some lenders add custom stages based on loan type, team structure, or approval process.
How do you build a loan pipeline?
To build a loan pipeline, define standard stages, create consistent workflows, assign ownership, centralize documents and communication, automate tasks, and review performance regularly. The goal is to create a repeatable process that moves loans toward funding with fewer gaps.
Why is mortgage loan pipeline management important?
Mortgage loan pipeline management helps lenders improve visibility, prioritize work, reduce bottlenecks, forecast funding volume, and improve borrower communication. It also helps managers identify problems before they affect closing timelines.
What metrics should lenders track in a loan pipeline?
Lenders should track active loans, stage conversion rates, pipeline aging, time in each stage, approval rate, pull-through rate, funding volume, fallout rate, and average time to close. These metrics help teams understand pipeline health and operational performance.
How can automation improve loan pipeline management?
Automation can route tasks, trigger reminders, request documents, update statuses, assign ownership, and alert teams when files need attention. This reduces manual follow-up and helps loans move through the pipeline more consistently.
What causes delays in the loan pipeline?
Common causes include missing documents, manual approvals, slow borrower responses, underwriting delays, compliance reviews, poor communication, unclear ownership, duplicate data entry, and limited visibility.
How does Mortgage Automator help manage the loan pipeline?
Mortgage Automator helps lenders manage the loan pipeline with workflow automation, pipeline dashboards, task management, document management, reporting, compliance tracking, and centralized borrower records.